This page has a free Rule of 72 calculator that does the math for you. It also checks the result against the exact doubling time, and it works for inflation and debt too.
Rule of 72 Calculator
Years to double = 72 ÷ rate · checked against the exact ln(2) ÷ ln(1 + r) · results update as you type
Growing your money takes time. However, compound interest can make that journey faster than many people expect. Whether you’re saving for retirement, building an investment portfolio, or comparing savings accounts, understanding how money grows can improve your financial decisions.
The Rule of 72 offers a simple way to estimate how long an investment needs to double. You only need one number: your expected annual interest rate. This mathematical shortcut helps you understand investment growth without complicated calculations.
A Rule of 72 calculator makes this process even easier. It shows your estimated doubling period and helps you compare different annual returns. You can use it to explore savings goals, retirement plans, and hypothetical investment opportunities.
How to Use the Rule of 72 Calculator
Calculating investment doubling time doesn’t require advanced financial knowledge. Enter your expected annual interest rate and use the calculator to estimate how many years your money needs to double. This method works best when you assume a consistent annual compound return.
Enter Your Annual Interest Rate
Start by entering your expected annual interest rate as a percentage. For example, you might enter 5%, 7%, or 10%. Use an annual growth rate rather than a monthly rate. Your assumption should reflect the investment’s expected yearly return.
Calculate How Many Years It Takes to Double Your Money
Once you enter the rate, the calculator divides 72 by your percentage. The result represents the estimated number of years needed to double your starting balance. A higher annual percentage return generally produces a shorter doubling period.
Understand Your Results with a Practical Example
Suppose you invest $10,000 at an assumed annual return of 8%. Dividing 72 by eight gives nine years. Your investment could reach approximately $20,000 after that period. This example assumes consistent annual growth without withdrawals or additional deposits.
What Is the Rule of 72?
The Rule of 72 is a financial shortcut that estimates how long money takes to double through compound growth. It connects an annual interest rate with an investment’s doubling period. Investors use it to understand how quickly savings or investments might grow over time.
This method works because compound interest generates earnings on your original principal and previously accumulated interest. As time passes, those earnings can produce further growth. The result is exponential growth rather than a simple, fixed-dollar increase.
Understanding the Relationship Between Interest and Doubling Time
Imagine depositing $5,000 into an account earning 8% annually. Your balance grows as interest accumulates on previous earnings. The longer you leave the money invested, the greater the effect of compounding. This relationship explains why investment time matters.
Why Investors Use the Rule of 72
Investors use this method to compare potential growth rates and evaluate financial goals. It can help you understand savings account interest, retirement savings, and hypothetical stock market returns. It also makes the time value of money easier to understand when planning long-term investments.
Rule of 72 Formula and How to Calculate It
The Rule of 72 formula connects the annual interest rate with the time required to double an investment. It provides a quick estimate without requiring a financial calculator. The calculation is especially convenient when comparing several possible investment returns.
The Basic Rule of 72 Mathematical Formula
The standard formula is:
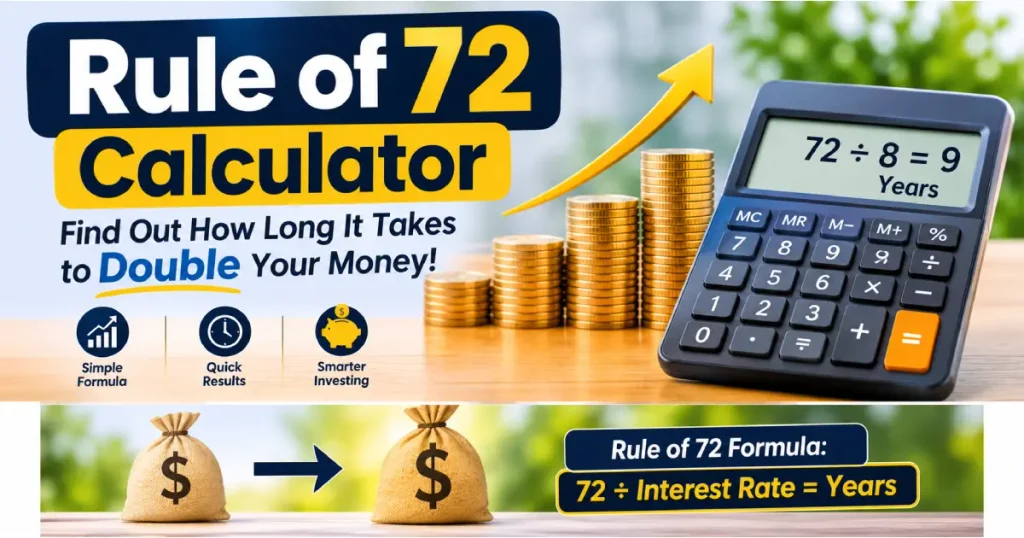
Doubling Time = 72 ÷ Annual Interest Rate (%)
For example, an investment earning 6% annually has an estimated doubling period of 12 years. Divide 72 by six to get the answer. The interest rate must appear as a whole percentage.
How to Find the Required Annual Return
You can also reverse the calculation when you know your financial deadline. Divide 72 by the number of years available to estimate the required annual return.
Required Annual Return = 72 ÷ Years to Double
For example, doubling an investment within eight years requires approximately 9% annual growth. This estimate can help establish a financial target. However, it doesn’t guarantee that an investment will achieve that return.
Why Does the Formula Use 72? (The Mathematics Behind It)
The number 72 offers convenient division by several common interest rates. It also provides a useful approximation of the mathematics behind compound growth. The natural logarithm of two, approximately 0.6931, forms the foundation of an exact doubling calculation.
The underlying relationship uses logarithms:
Exact Doubling Time = ln(2) ÷ ln(1 + r)
Here, r represents the annual interest rate as a decimal. The shortcut replaces this more complex calculation with an easy mental estimate. That’s why 72 remains popular in financial education.
How Long Does It Take to Double Your Money at Different Interest Rates?
Your annual return has a direct effect on investment doubling time. A higher growth rate shortens the estimated waiting period. Even a small difference can matter when you invest for several decades. The following examples show how different rates affect potential growth.
Doubling Your Money at 4%, 6%, 8%, and 10%
Consider these common hypothetical investment returns. Each rate produces a different estimated doubling period.
| Annual return | Estimated doubling time |
| 4% | 18 years |
| 5% | 14.4 years |
| 6% | 12 years |
| 7% | 10.29 years |
| 8% | 9 years |
| 10% | 7.2 years |
| 12% | 6 years |
These figures use the Rule of 72. They assume consistent annual growth and exclude taxes and fees. Actual results may differ, especially when market returns change from year to year.
How Long Does It Take to Double Money at 7% Interest?
At a 7% annual return, the calculation produces approximately 10.29 years. A $5,000 investment could therefore grow to around $10,000 over that period. This example illustrates how compound interest supports gradual wealth accumulation.
Real-Life Investment Doubling Examples
Consider three investors who each earn an assumed 8% annual return. One starts with $1,000, another invests $5,000, and the third deposits $10,000. Their estimated doubling period remains nine years because the growth rate stays identical.
| Starting investment | Approximate doubled value | Estimated time |
| $1,000 | $2,000 | 9 years |
| $5,000 | $10,000 | 9 years |
| $10,000 | $20,000 | 9 years |
The starting balance changes the dollar amount earned. However, it doesn’t change the estimated doubling period when the percentage return remains constant.
How Accurate Is the Rule of 72?
The Rule of 72 provides a useful estimate rather than an exact financial result. Its accuracy depends on the annual interest rate and compounding assumptions. It generally performs well around common investment return levels, particularly near 8%.
Rule of 72 vs. Exact Compound Interest Calculation
The exact formula calculates doubling time using logarithms. It accounts for the mathematical relationship between the interest rate and compound growth.
Exact formula:
t = ln(2) / ln(1 + r)
Here, t represents the number of years and r represents the annual rate in decimal form. Unlike the shortcut, this calculation provides a more precise result for a fixed annual compounding rate.
Accuracy at Different Interest Rates (2%–24%)
The following table compares estimated doubling periods with exact annual compounding results.
| Annual rate | Rule of 72 | Exact doubling time |
| 2% | 36.00 years | 35.00 years |
| 4% | 18.00 years | 17.67 years |
| 6% | 12.00 years | 11.90 years |
| 8% | 9.00 years | 9.01 years |
| 10% | 7.20 years | 7.27 years |
| 12% | 6.00 years | 6.12 years |
| 14% | 5.14 years | 5.29 years |
| 16% | 4.50 years | 4.67 years |
| 18% | 4.00 years | 4.19 years |
| 20% | 3.60 years | 3.80 years |
| 22% | 3.27 years | 3.49 years |
| 24% | 3.00 years | 3.22 years |
The comparison shows that the shortcut performs particularly well near 8%. Differences become more noticeable at higher rates. These results assume a constant effective annual return and annual compounding.
How to Improve the Accuracy of the Rule of 72
Use the exact logarithmic formula when precision matters. For accounts with monthly or daily compounding, convert the stated interest rate into an effective annual rate first. This adjustment prevents differences in compounding frequency from distorting your estimate.
Rule of 72 vs. Rule of 70, 114, and 144
Several financial shortcuts help estimate investment growth. The Rule of 70 and Rule of 72 estimate doubling time. Meanwhile, the Rules of 114 and 144 estimate how long money takes to triple or quadruple.
Rule of 70 for Estimating Investment Growth
The Rule of 70 divides 70 by the annual growth rate. It estimates how many years an investment needs to double. Its results can be useful at certain interest rates. Comparing a Rule of 70 calculator with a Rule of 72 calculator shows how different approximation constants affect the result.
Rule of 114 for Tripling Your Money
The Rule of 114 estimates how long an investment takes to reach three times its starting value. Divide 114 by the annual growth rate. At an assumed 6% return, the estimated tripling period is 19 years.
Rule of 144 for Quadrupling Your Investment
The Rule of 144 estimates the time required to quadruple an investment. Divide 144 by the annual interest rate. At an assumed 8% annual return, the estimated period is 18 years.
Which Rule Should You Use for Financial Planning?
Each shortcut serves a different purpose. Choose the calculation that matches your financial goal. The following comparison summarizes their applications.
| Financial rule | Growth milestone | Formula |
| Rule of 70 | Double | 70 ÷ Rate |
| Rule of 72 | Double | 72 ÷ Rate |
| Rule of 114 | Triple | 114 ÷ Rate |
| Rule of 144 | Quadruple | 144 ÷ Rate |
These methods work best as quick estimates. Use an investment growth calculator when you need more detailed projections.
How to Use the Rule of 72 for Inflation and Debt
Investment growth isn’t the only situation where this shortcut proves useful. Inflation reduces purchasing power over time while compound interest can increase unpaid debt. Both situations involve percentage changes that accumulate across multiple years.
How Inflation Reduces the Purchasing Power of Money
Inflation makes goods and services more expensive. As prices rise, the same amount of money buys fewer products. For example, a household spending $100 on groceries today may need more money for similar items later.
How Long Does It Take for Inflation to Halve Your Money’s Value?
The shortcut estimates how quickly inflation can reduce purchasing power by half. At 4% annual inflation, dividing 72 by four gives approximately 18 years. Therefore, $100 could have the purchasing power of roughly $50 after that period.
This is an approximation rather than an exact inflation forecast. A dedicated inflation rate calculator can provide more detailed purchasing-power comparisons using different assumptions.
How Quickly Can Credit Card Debt Double?
Suppose a credit card balance grows at an assumed 18% annual compound rate without payments or additional charges. Dividing 72 by 18 produces approximately four years. Actual credit card balances depend on daily periodic rates, payments, fees, and new purchases.
Rule of 72 for Different Types of Investments
Different investments have different growth patterns. A savings account may offer a stated interest rate, while stocks experience changing market returns. Understanding these differences helps you apply the shortcut more responsibly across your investment portfolio.
Savings Accounts and Fixed Deposits
Savings accounts and certificates of deposit offer interest based on their account terms. A fixed rate can make doubling estimates easier. However, variable account rates may change over time. Always distinguish the nominal interest rate from the effective annual rate.
Stocks and Mutual Funds
Stocks and mutual funds can produce growth through price increases and reinvested dividends. However, stock market returns fluctuate. An assumed 8% annual return doesn’t mean an investment earns exactly 8% every year. Market losses can also delay or reverse investment growth.
Retirement Savings and Long-Term Investments
Retirement accounts such as 401(k)s and IRAs can benefit from long investment periods. Reinvested earnings may support substantial growth over several decades. Employer matching and regular contributions can further increase retirement savings, although the basic doubling formula doesn’t include those deposits.
Real Estate and Other Investment Opportunities
Property investors may use the shortcut to estimate hypothetical appreciation. However, real estate involves maintenance, financing costs, property taxes, and transaction expenses. Rental income also changes the overall return. These factors make property investment more complex than a simple interest calculation.
What Are the Limitations of the Rule of 72?
Although the shortcut is useful, it doesn’t represent every detail of an investment. Actual returns can change because of market conditions, taxes, fees, and withdrawals. Understanding these limitations helps prevent unrealistic financial expectations.
Why Variable Investment Returns Affect Doubling Time
Investment returns rarely remain identical every year. A portfolio might gain 12% one year and lose 8% the next. Even when its average return appears attractive, the actual growth path can differ from a steady-return projection.
How Taxes and Investment Fees Change Your Results
Taxes can reduce investment earnings depending on the account type and applicable tax rules. Investment management fees also reduce net returns. Therefore, calculate growth using an appropriate after-fee rate when evaluating your actual investment progress.
Why Regular Contributions Are Not Included in the Basic Formula
The basic formula assumes one starting investment. It doesn’t account for monthly deposits or withdrawals. For recurring contributions, an annuity calculation provides a more suitable approach because each deposit has a different amount of time to grow.
The Difference Between Estimated and Guaranteed Returns
A mathematical estimate isn’t a promise of future performance. Some qualifying bank deposits receive FDIC protection within applicable coverage limits. However, stocks and mutual funds don’t receive the same protection against market losses. Always understand the investment risk before committing money.
Rule of 72 vs. Future Value Calculator
The Rule of 72 estimates how long an investment may take to double. A Future Value Calculator answers a different question: how much could an investment be worth after a selected period? Both methods support financial planning but serve different purposes.
Rule of 72 for Quick Investment Estimates
Use the shortcut when you want a fast doubling estimate. For example, an assumed 8% annual return suggests approximately nine years. It provides a useful starting point when comparing potential growth rates without calculating the full future balance.
Future Value Formula for Accurate Compound Growth
The standard future value formula calculates the projected balance of a single investment:
FV = PV × (1 + r)ⁿ
Here, FV represents the future investment value. PV means the present value or starting principal. The variable r represents the annual interest rate in decimal form. Finally, n represents the number of annual compounding periods.
For example, investing $10,000 at an assumed 8% annual return for ten years produces approximately $21,589. This calculation provides a more detailed projection than a doubling-time estimate.
When Should You Use Each Calculation Method?
Choose the doubling shortcut when you want to estimate how quickly money might grow. Use a Future Value Calculator when you need a projected dollar amount for a specific period. A Compound Interest Calculator can also help compare different contribution and compounding scenarios.
FAQs
How Do You Calculate the Rule of 72?
Divide 72 by the annual interest rate. For example, at 8% interest, your money may double in approximately 9 years.
How Long Does It Take to Double Money at 7% Interest?
At a 7% annual return, your money may double in about 10.29 years, assuming consistent compound growth.
What Return Do I Need to Double My Money in 10 Years?
You need an estimated annual return of 7.2% to double your money in 10 years.
Is the Rule of 72 Accurate for Long-Term Investments?
The Rule of 72 gives a quick estimate, but actual returns may vary due to market changes, taxes, and fees.
Why Is It Called the Rule of 72 Instead of 70?
The number 72 is easy to divide by many common interest rates and provides a useful estimate of investment doubling time.
Does the Rule of 72 Work With Monthly Compounding?
Yes. First, convert the monthly-compounded rate into an effective annual rate, then divide 72 by that rate.
Can I Use the Rule of 72 for Monthly Investments?
The basic Rule of 72 does not include regular deposits. Use a Future Value of Annuity Calculator to estimate monthly investment growth.
Can the Rule of 72 Calculate Inflation and Debt Growth?
Yes. It can estimate how quickly inflation reduces purchasing power or compound interest increases debt over time.
How Do I Calculate the Rule of 72 in Excel?
Enter the annual interest rate as a whole number in cell A1 and use =72/A1. If A1 contains 8, Excel returns 9 years.
Final Thoughts
Understanding how money grows can change the way you approach saving and investing. The Rule of 72 makes compound growth easier to understand by turning an annual return into an estimated doubling period. It also helps compare different investment assumptions without complicated mathematics.
However, every investment carries different costs and risks. Interest rates can change, markets can decline, and inflation can reduce purchasing power. Consider these factors before relying on any growth projection. Combine simple estimates with detailed financial calculations to make more informed decisions.
The most valuable part of compound growth is time. Starting early and maintaining consistent saving habits can make a meaningful difference to your financial future.
Sources and Further Reading
For additional financial education and reliable information, consult these authoritative resources:
Investor.gov – Compound Interest and Investment Education
FDIC – Deposit Insurance and Banking Information
IRS – Retirement Plans and Tax Information
U.S. Bureau of Labor Statistics – Consumer Price Index
Federal Reserve – Economic Data and Interest Rates
Key Takeaways
- ✓ Estimate investment doubling time: Divide 72 by the annual compound return rate (expressed as a percentage) to estimate how many years your money may take to double.
- ✓ Compare different growth rates: At 6% annual growth, money doubles in about 12 years. At 8%, it takes 9 years, while at 10%, it takes approximately 7.2 years.
- ✓ Understand the difference between estimated and exact results: At an 8% annual return, the Rule of 72 estimates 9 years, compared with approximately 9.01 years using the exact compound interest formula.
- ✓ Calculate your required return: If you want to double your investment in 10 years, the Rule of 72 suggests an annual compound return of approximately 7.2%.
- ✓ Consider the effect of inflation: At 3% annual inflation, the purchasing power of money takes approximately 24 years to fall to half its original level.
- ✓ Know the limitations: The basic Rule of 72 assumes a single investment and a constant growth rate. It does not include regular contributions, taxes, fees or changing market returns.
Rule of 72 Formula
Use this simple formula to estimate the time needed for an investment to double:
Years to Double = 72 ÷ Annual Return (%)Example: 72 ÷ 8 = 9 years. This is an approximation, not a guaranteed result.
Sources & Further Reading
- U.S. Securities and Exchange Commission: Compound Interest Calculator — Explore how compound interest can affect investment growth over time.
- Khan Academy: Financial Mathematics Learning Resources — Learn about compound interest and the mathematical principles behind investment growth.
- Mathematical reference: The Rule of 72 estimates doubling time using 72 divided by the annual return percentage. Exact results can be checked using logarithms and the compound growth formula.
- Calculation methodology: Examples on this page assume annual compounding and a constant annual rate unless otherwise stated.
Use our Best Financial Calculators:
We provide free online calculators with easy explanations. Every calculator is tested using standard formulas and updated regularly to improve accuracy.
Here are our best Calculator tools below:
Future Value Calculator, Present Value Calculator , Loan EMI Calculator,401k Calculator, SIP Calculator, Hourly to Salary Calculator , Future Property value calculator,
CPC,CPM & CTR Calculator, Losertown calorie calculator, Emergency Fund Calculator, Net Disposable Income (NDI)